

Loan program
Construction
Financing structured around a build, including conversations about one-time close options.
Overview
What it is
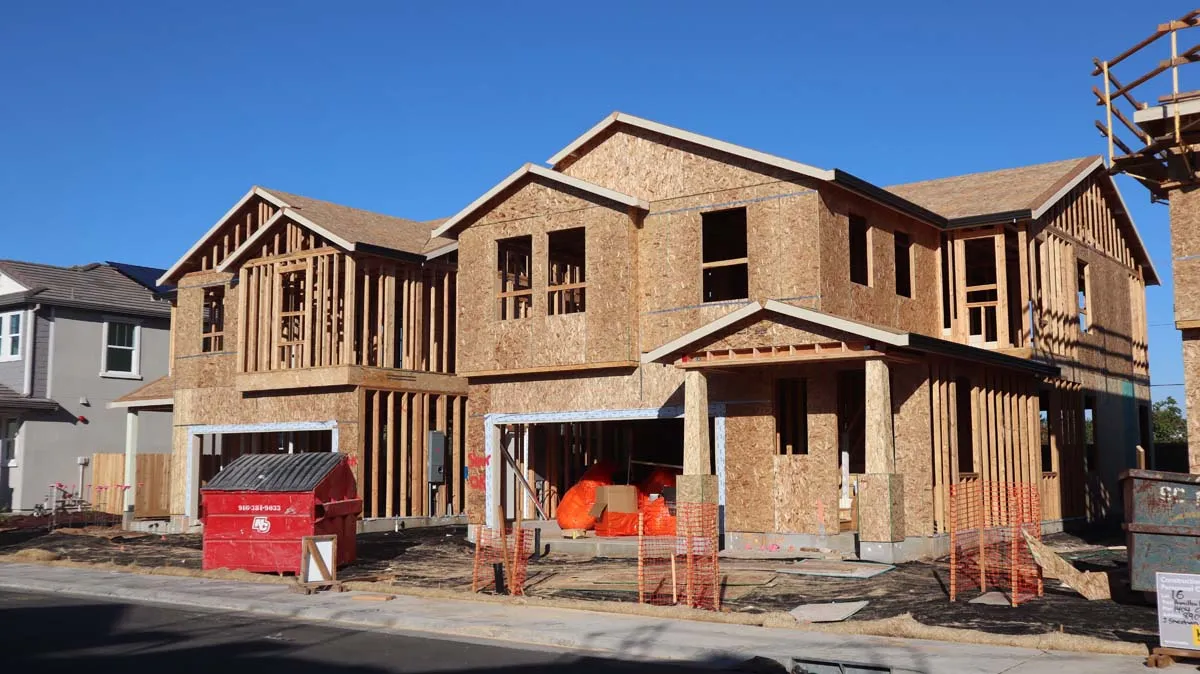
Construction financing is not a regular purchase mortgage with a later renovation. Money is typically disbursed in draws as the home is built, with inspections along the way.
Some borrowers use a construction-to-permanent or “one-time close” structure so they are not applying for a second loan when the house is finished. Others use a construction loan now and a separate permanent loan later. The right path depends on the builder, the lot, and the file.
Confirm with a Hancock loan officer that construction lending is available for your scenario and state before you sign a build contract that assumes a specific loan.
Who it may be good for
- Buyers working with a builder on a new home.
- Clients with land and plans who need a loan that funds during construction.
- Veterans and conventional borrowers who may have construction options. Eligibility is not one-size-fits-all.
How it works
- 01
Plans, specs, builder contract, and lot information come first, often before a full application looks like a purchase file.
- 02
During the build, inspections and draws have to match the work in place.
- 03
When the home is complete, the loan either converts to a permanent mortgage or is refinanced, depending on the structure you chose.
Potential advantages
- Aligns financing with how a house is actually built.
- A one-time close, when available, can reduce the need for a second application at the end.
Things to consider
- Builder experience, contract type, and contingency reserves matter as much as your credit score.
- Timelines slip. Rate locks and construction periods have to be planned, not hoped.
- Not every Hancock market or file will fit construction lending. Treat this as a specialist conversation.
Confirm this program with a Hancock loan officer before assuming it applies to your property or state.
Build, then live
Construction loans follow the job site. Draws, inspections, and a plan to convert to a permanent mortgage.
Common questions
Questions about Construction loans
Yes, or at least before you are contractually stuck. Loan structure, draw schedules, and what the investor will accept on the builder all affect whether the file can close.

Ready when you are
The house is the point.
Whether you’re buying your first home, moving into your next one, refinancing, or exploring your options, we’re here to help you figure out the next step.