

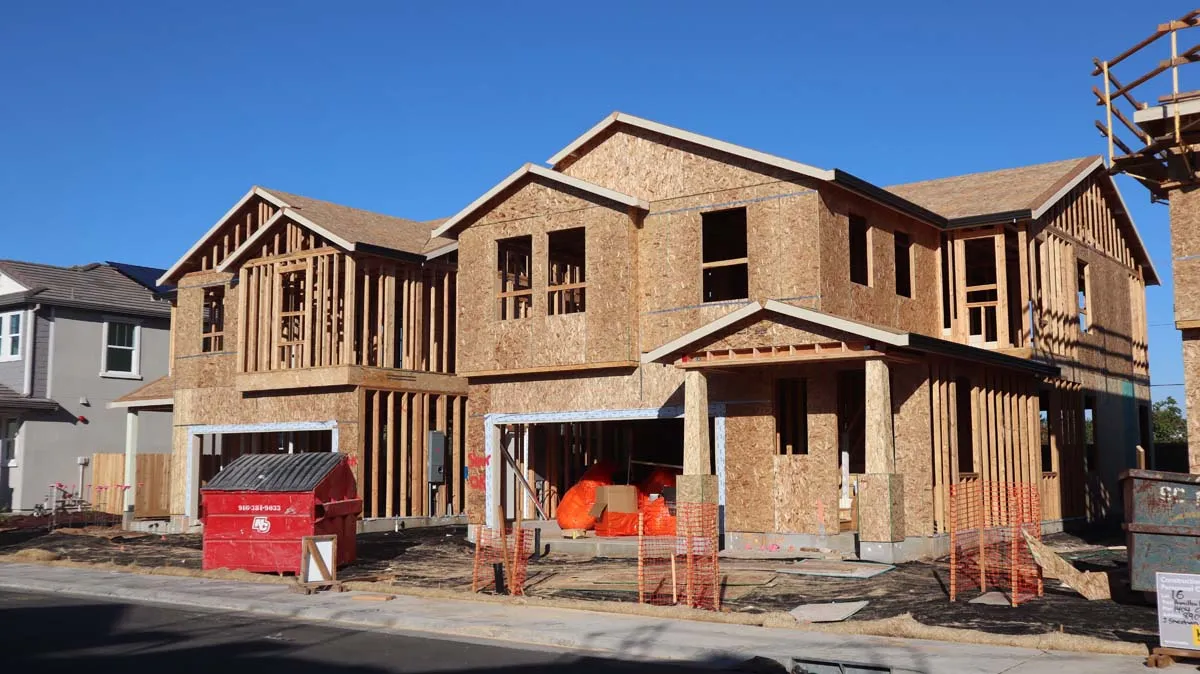
Build
Financing designed around the construction, not a finished house.
Talk through draws, the builder, and the lot before you are too far into plans.
This path
Construction files start with plans, specs, builder, and lot, not a finished-house application.
Who this is for
If this sounds like you.
Working with a builder
Land and plans
Need a specialist
What happens next
Three moves. Then a person.
01
Talk before ground-break
Lot, plans, builder, and timeline all change the loan.
02
Confirm the structure
One-time close, or construction then a separate permanent loan.
03
Keep draws honest
Inspections and disbursements have to match the build.
Build, then live
The loan has to follow the job site.
Draws, inspections, and a plan to convert to a permanent mortgage.
Programs often in play
Options, not a grid of logos.
Construction lending is not available in every scenario. Confirm product availability and licensing with a Hancock loan officer.
Common questions
What borrowers ask on this path

Ready when you are
The house is the point.
Whether you’re buying your first home, moving into your next one, refinancing, or exploring your options, we’re here to help you figure out the next step.